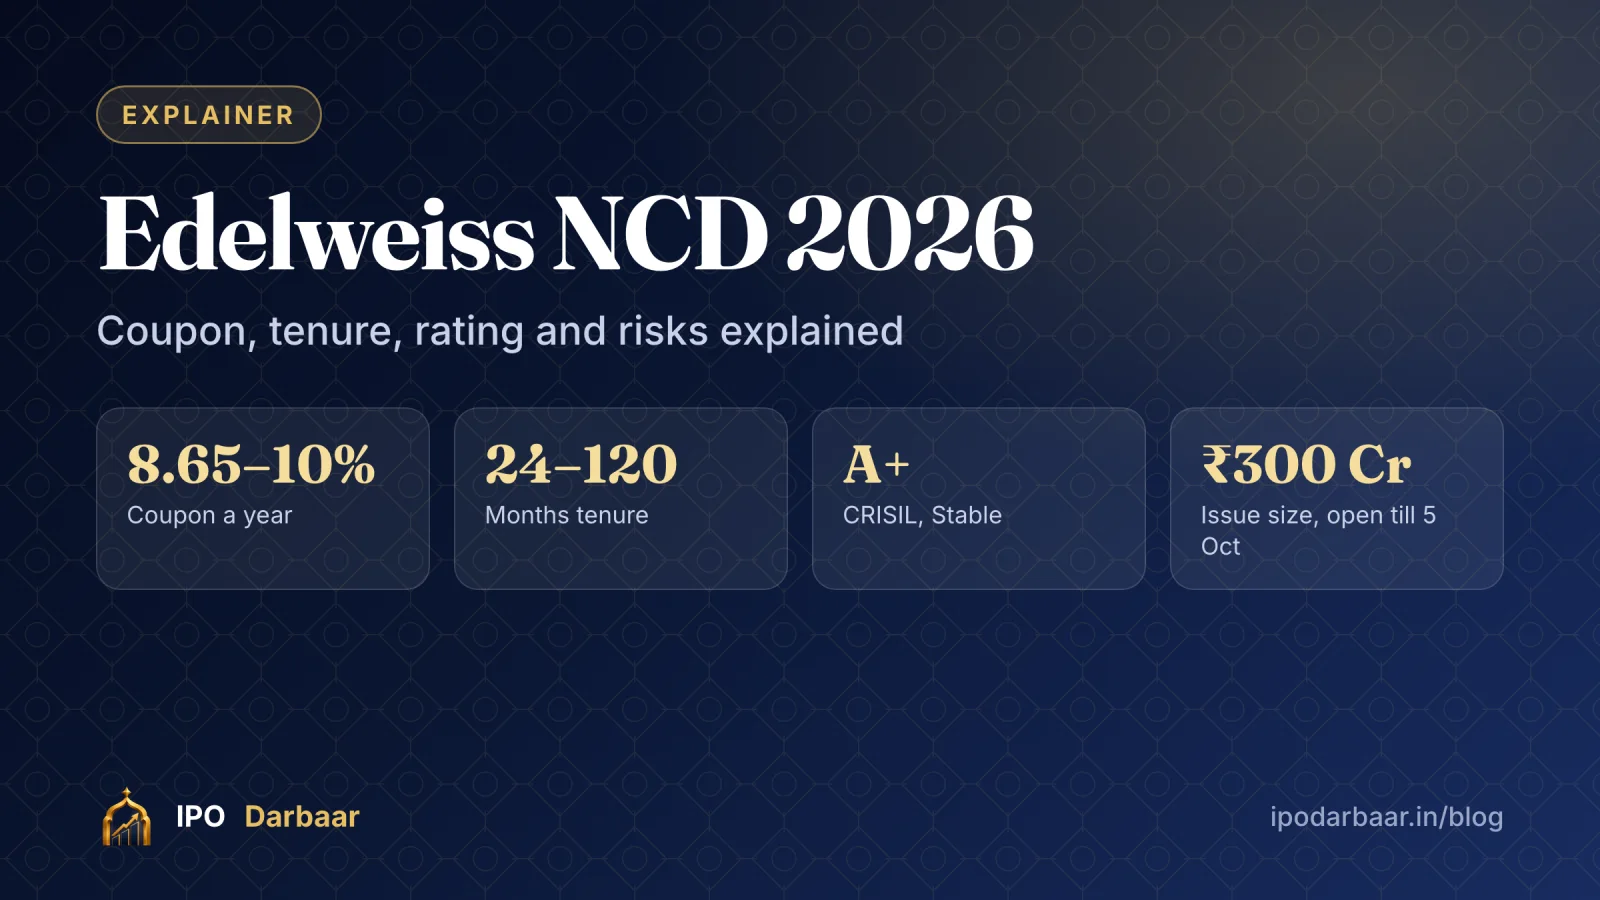
- Up to ₹300 crore of secured NCDs with coupons of 8.65% to 10.00% a year
- Tenors of 24, 36, 60 and 120 months, with monthly, annual and cumulative options
- Rated CRISIL A+/Stable; minimum investment ₹10,000 (10 NCDs)
- Open from 21 September to 5 October 2026; listed on BSE
In this post
Edelweiss Financial Services has opened a public issue of secured, redeemable non-convertible debentures (NCDs). The base issue is ₹150 crore with a green shoe option to keep another ₹150 crore, so the company can raise up to ₹300 crore. The issue opened on 21 September and is scheduled to close on 5 October 2026, and the NCDs will be listed on BSE.
Here is how the issue works, what the rating means and what to weigh before you apply.
Edelweiss NCD at a glance
| Detail | Edelweiss Financial Services NCD |
|---|---|
| Type | Secured, redeemable non-convertible debentures |
| Issue size | ₹150 crore base + ₹150 crore green shoe = up to ₹300 crore |
| Coupon | 8.65% to 10.00% a year, depending on the series |
| Tenure | 24, 36, 60 and 120 months |
| Series and options | 10 series with monthly, annual and cumulative interest |
| Credit rating | CRISIL A+/Stable |
| Face value | ₹1,000 per NCD |
| Minimum application | ₹10,000 (10 NCDs) |
| Issue dates | 21 September to 5 October 2026 |
| Listing | BSE |
What an NCD is
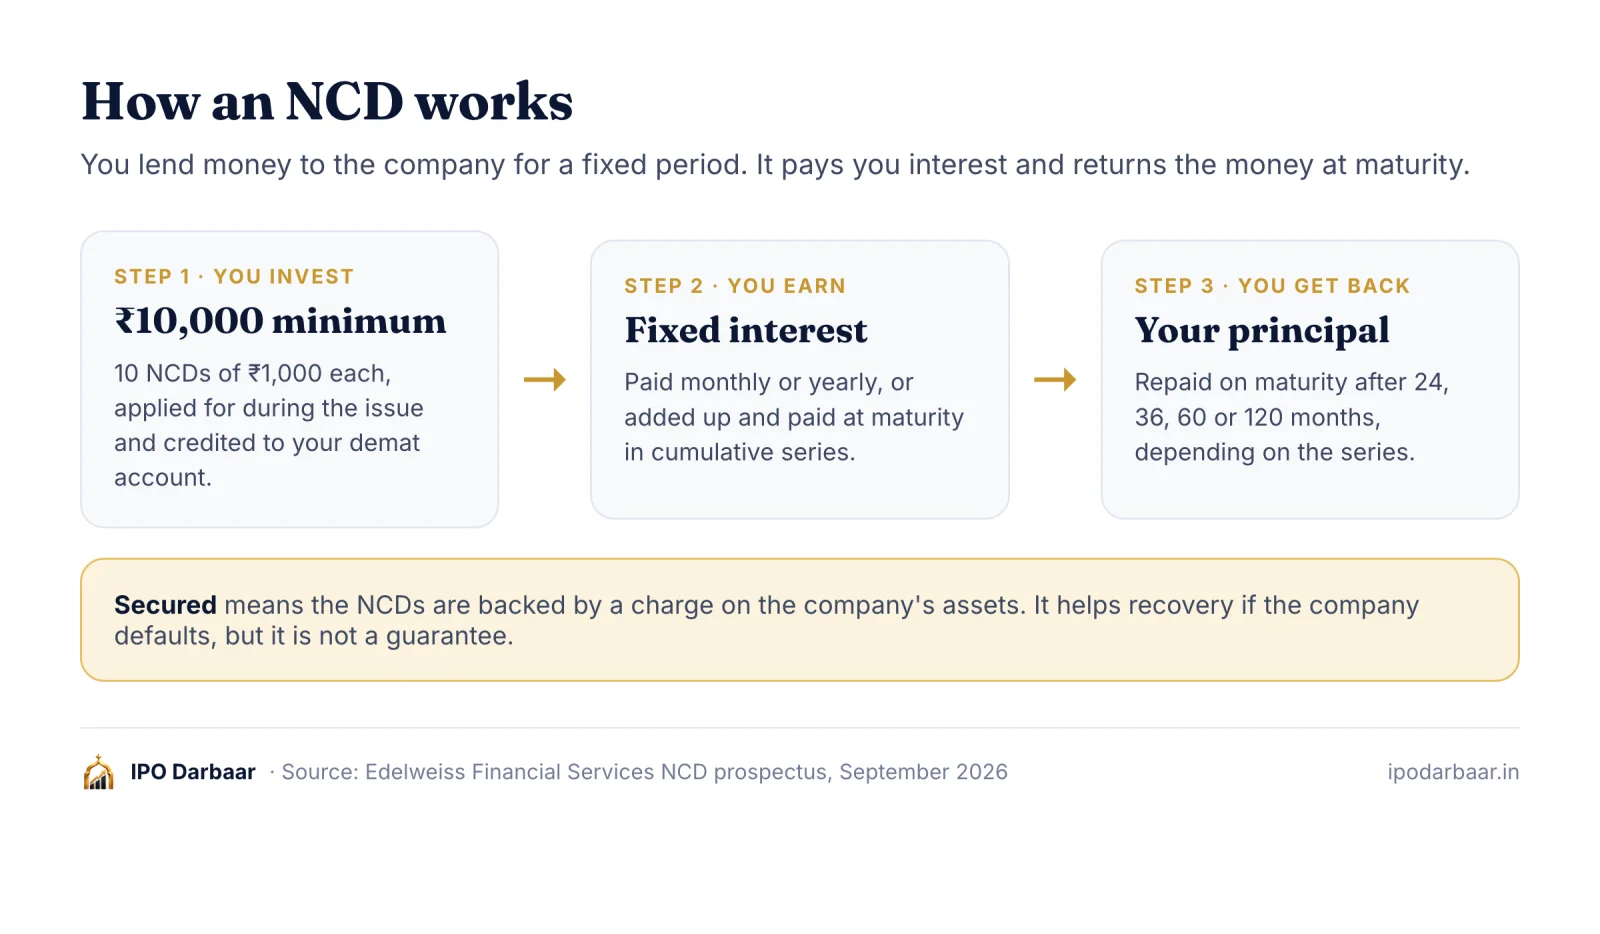
An NCD is a loan you give to a company. The company pays you a fixed rate of interest and returns your money on the maturity date. Unlike convertible debentures, NCDs can never be turned into shares, so you do not share in the company's growth; you simply earn the agreed interest.
"Secured" means the NCDs are backed by a charge on the company's assets. If the company defaults, secured lenders have a claim on those assets before unsecured creditors. That improves the chances of recovery but does not remove the risk: recovery can take years and may not be complete.
What "base issue" and "green shoe" mean
The company has asked for ₹150 crore (the base issue) but can keep up to another ₹150 crore if demand is strong (the green shoe option). If investors apply for less than ₹150 crore, the company raises only what it receives, subject to the minimum subscription in the prospectus. If they apply for more than ₹300 crore, the extra applications are not allotted and the money is released.
Series and interest options
The issue has ten series. They differ in tenure (24, 36, 60 or 120 months) and in how interest is paid:
- Monthly: interest is paid into your bank account every month. This suits investors who want regular income.
- Annual: interest is paid once a year.
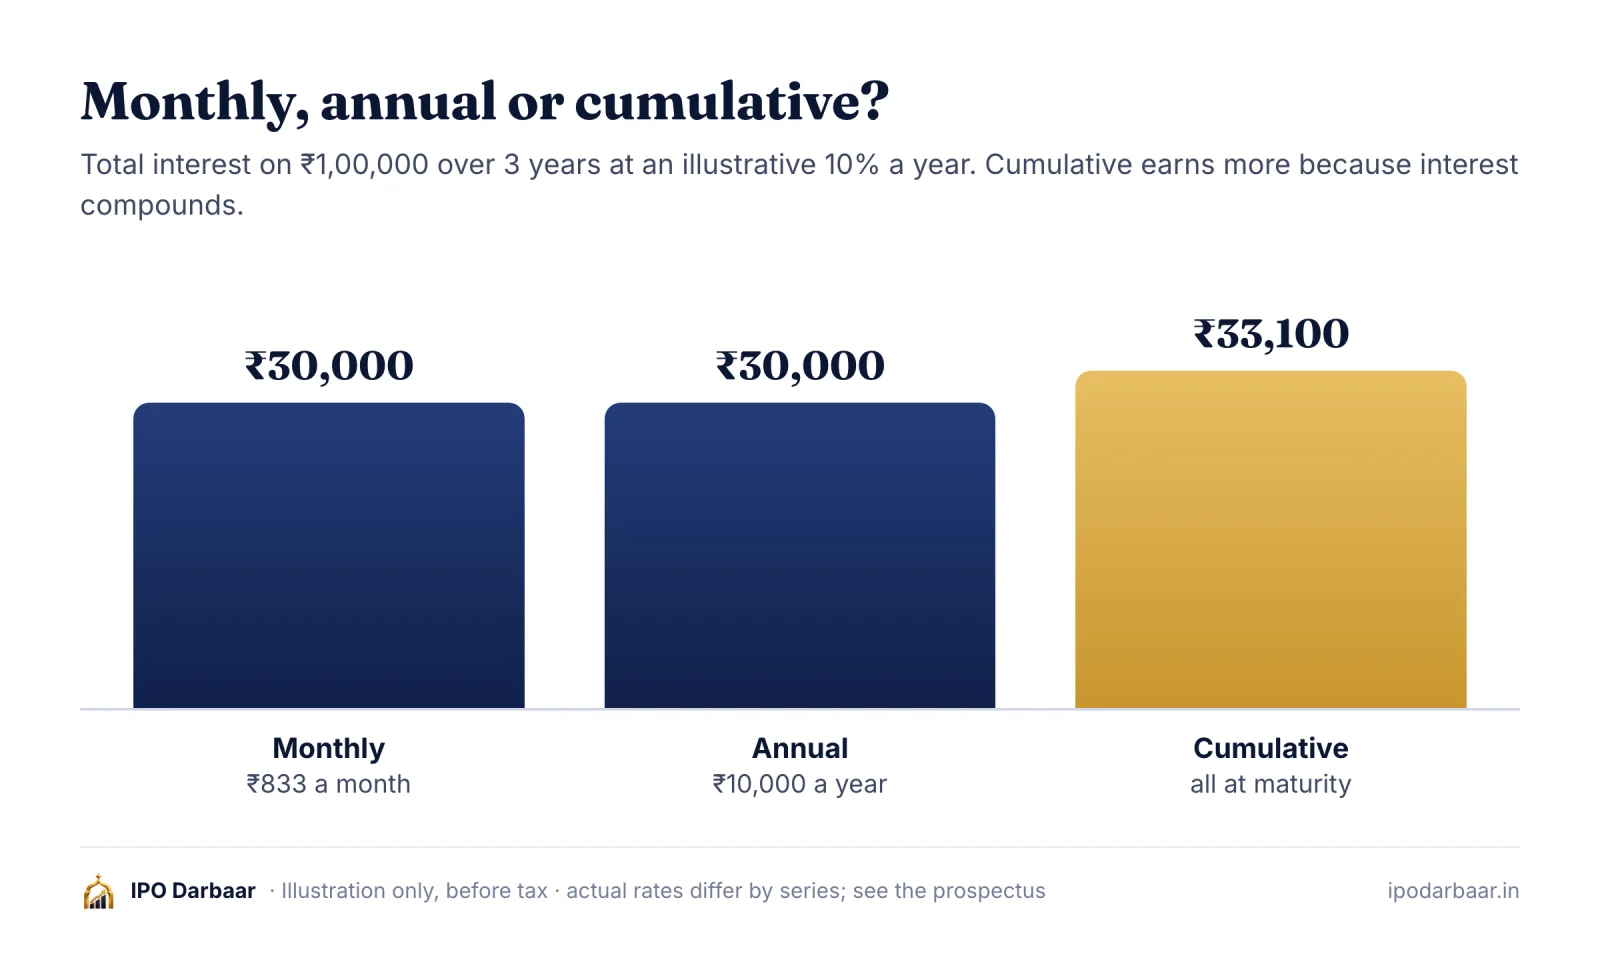
- Cumulative: nothing is paid until maturity, when you receive the principal plus all the interest. Because interest compounds, the effective yield is a little higher than a series with the same rate that pays out.
The coupon ranges from 8.65% to 10.00% a year depending on the series. Check the series table in the prospectus for the exact rate, yield and maturity amount of the series you choose. As an illustration only, ₹1 lakh in a series paying 10% a year annually would earn ₹10,000 a year before tax.
Coupon vs effective yield
The coupon is the stated interest rate. The effective yield is what you actually earn after accounting for when interest is paid. In a cumulative series, interest is added to your principal and earns interest itself, so the effective yield is higher than the same coupon paid out every year. In many NCD issues the monthly series carries a slightly lower coupon than the annual one so that their effective yields line up. Compare the effective yield column in the prospectus rather than the coupon alone.
What the A+ rating means
CRISIL rates the issue A+ with a Stable outlook. In CRISIL's scale, instruments rated A are considered to have an adequate degree of safety regarding timely payment of interest and principal, and carry low credit risk. The "+" shows the issue is at the stronger end of the A category, and a Stable outlook means CRISIL does not expect the rating to change soon.
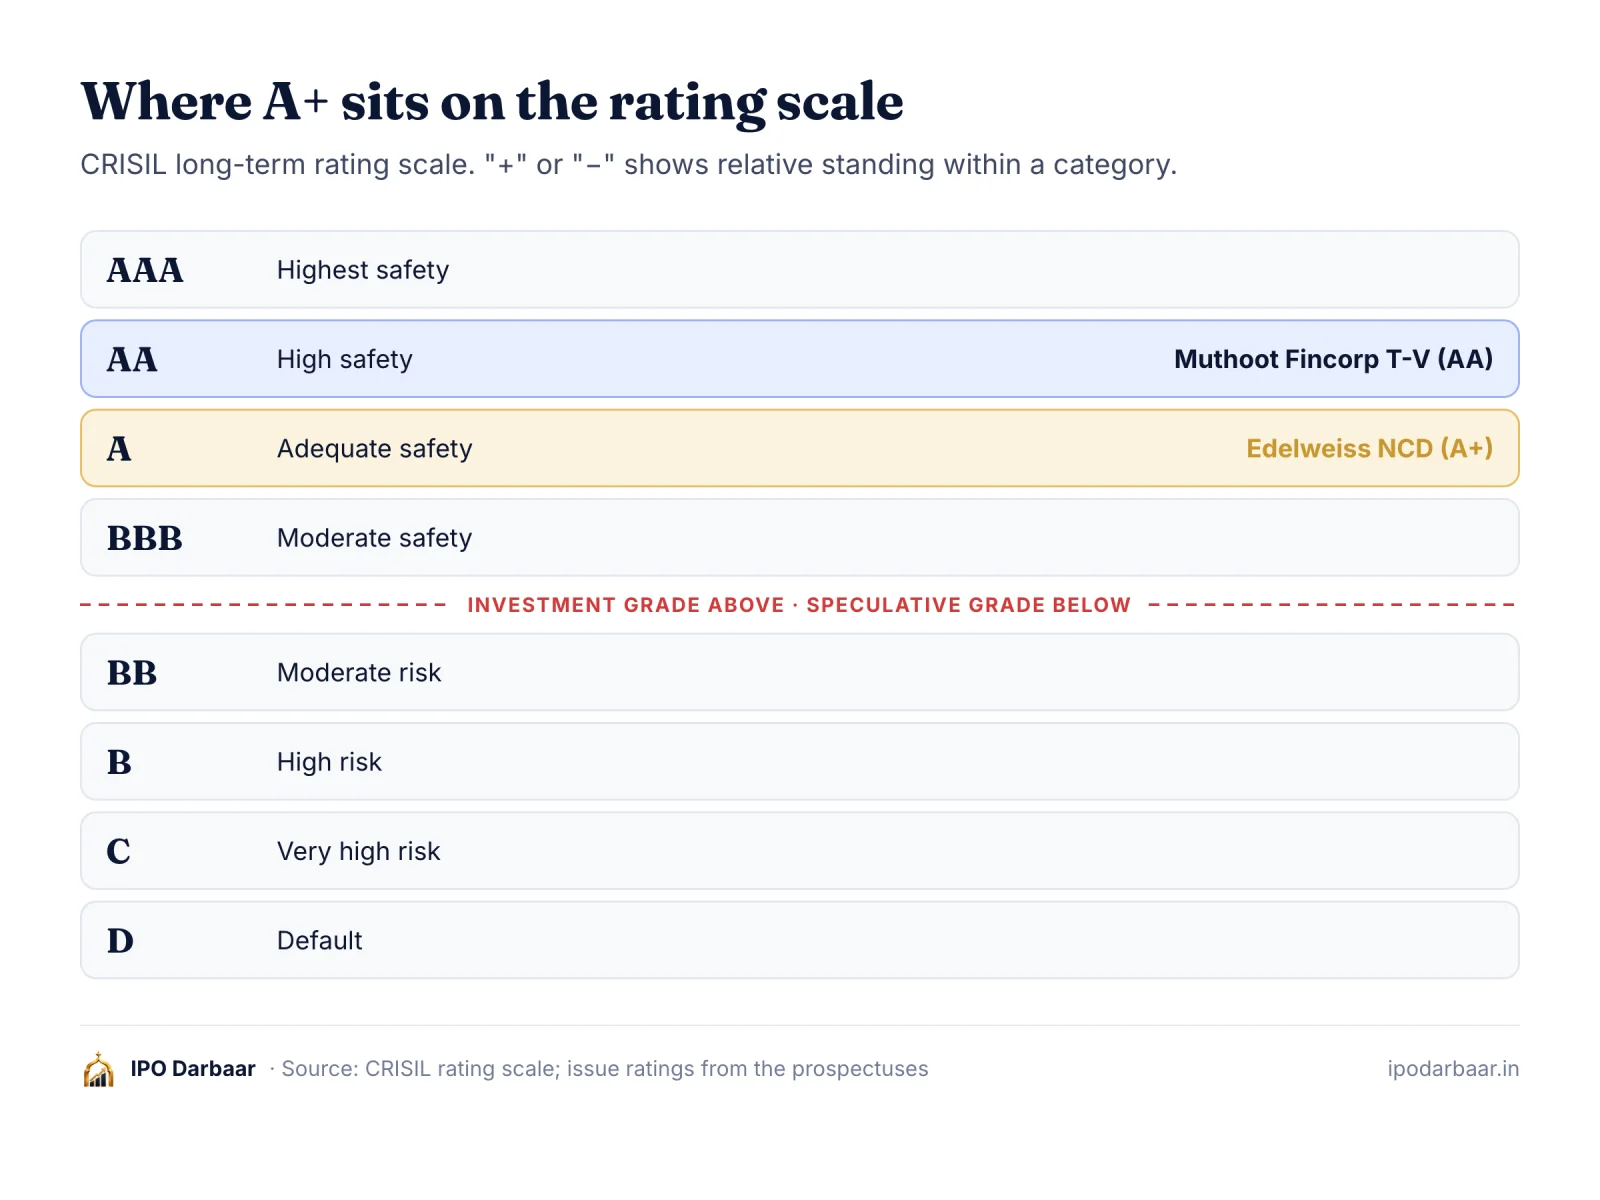
A is below AAA and AA, so the issue pays more to make up for the extra risk. For comparison, Muthoot Fincorp's Tranche V issue in September was rated CRISIL AA/Stable and offered 8.56% to 9.25%. A rating is an opinion, not a guarantee, and it can be downgraded during the life of the NCD.
Risks to weigh
- Credit risk: the company may delay or miss interest or principal payments.
- Liquidity: the NCDs will be listed on BSE, but retail NCDs often trade thinly. If you need the money before maturity, you may have to sell at a discount.
- Interest rates: if rates rise after you invest, newer issues will pay more and the market price of your NCDs may fall. This matters most for the longer 60 and 120-month series.
- Concentration: putting a large part of your savings into one company's debt adds risk. Spreading money across issuers and instruments lowers it.
NCD vs bank fixed deposit
NCDs are often compared with fixed deposits because both pay a fixed rate for a fixed period. The differences matter more than the rate:
| Bank fixed deposit | Edelweiss NCD | |
|---|---|---|
| Who you lend to | A bank | A listed financial services company |
| Safety net | DICGC insurance up to ₹5 lakh per depositor per bank | No insurance; secured by a charge on the company's assets |
| Rate | Usually lower | 8.65% to 10.00% a year |
| Getting money back early | Break the FD with a small penalty | Sell on BSE at the market price, which may be below face value |
| Tax on interest | Slab rate; TDS may apply | Slab rate; TDS may apply |
| Minimum | Often ₹1,000 or less | ₹10,000 (10 NCDs) |
The extra interest on an NCD is payment for taking on the company's credit risk and for giving up easy access to your money. Many investors keep NCDs to a part of their fixed-income savings and spread it across issuers.
Tax on NCD interest
Interest from NCDs is added to your income and taxed at your slab rate. Tax may also be deducted at source (TDS) on the interest; the prospectus explains when TDS applies and how to submit Form 15G or 15H if you are eligible. If you sell the NCDs on the exchange before maturity, the profit or loss is treated as a capital gain, and the rate depends on how long you held them. The capital gains tax calculator can help you estimate it.
How to apply
You can apply during the issue period through your broker's app (usually under the IPO or bonds section) or through your bank's net banking using ASBA, which blocks the money in your account until allotment. Choose the series and the number of NCDs, with a minimum of 10 NCDs (₹10,000). You need a demat account, as the NCDs are credited in demat form.
Public NCD issues are generally allotted on a first-come, first-served basis by date of application, and a company can close an issue early if it is fully subscribed. If you plan to apply, check the latest subscription and any early-closure notice. The Edelweiss NCD page has the issue details, and our October roundup lists the other NCDs, rights issues and buybacks that are open.
Frequently asked questions
What is the minimum investment in the Edelweiss NCD?
₹10,000, which buys 10 NCDs of ₹1,000 each. You can apply for more in multiples of one NCD, across one or more series.
When does the Edelweiss NCD issue close?
It is scheduled to close on 5 October 2026. Public NCD issues can close earlier if they are fully subscribed and the company decides to close early.
Is the interest taxable?
Yes. NCD interest is added to your income and taxed at your slab rate. TDS may be deducted; the prospectus explains when, and how to submit Form 15G or 15H if you are eligible.
Can I sell the NCDs before maturity?
Yes, once they are listed on BSE you can sell them through your broker. The price depends on demand and on interest rates at the time, and trading in retail NCDs is often thin, so you may get less than ₹1,000 per NCD.
What does CRISIL A+/Stable mean?
CRISIL considers A-rated debt to have an adequate degree of safety for timely payment, with low credit risk. "+" places it at the upper end of the A category, and "Stable" means no change in the rating is expected soon.
For information and education only; not investment advice. Figures come from offer documents, exchange and SEBI filings and IPO Darbaar data as of the date of publishing. Grey market premium (GMP) is unofficial.