- Only shareholders on the record date get rights, in a fixed ratio to their holding
- Rights entitlements (REs) reach your demat account and can be used, sold or left to lapse
- Not subscribing dilutes your stake; letting REs lapse means getting nothing for them
- In partly paid issues you pay part of the price now and the rest in later calls
In this post
- What is a rights issue?
- Why companies choose a rights issue
- Key terms
- Rights issue vs bonus issue vs FPO
- Example 1: Tuni Textile Mills, 15 for 4 at ₹1
- Example 2: Jaykay Enterprises, 3 for 19 at ₹75, partly paid
- The discount is not free money
- Your options: subscribe, sell or let lapse
- How to apply
- Frequently asked questions
A rights issue is a way for a listed company to raise money from the people who already own it. The company offers new shares to its existing shareholders, in proportion to what they hold and usually at a price below the market price. If you own shares, sooner or later you will receive one of these offers, and doing nothing is usually the costliest choice.
This post explains the key terms and works through two real rights issues from September 2026.
What is a rights issue?
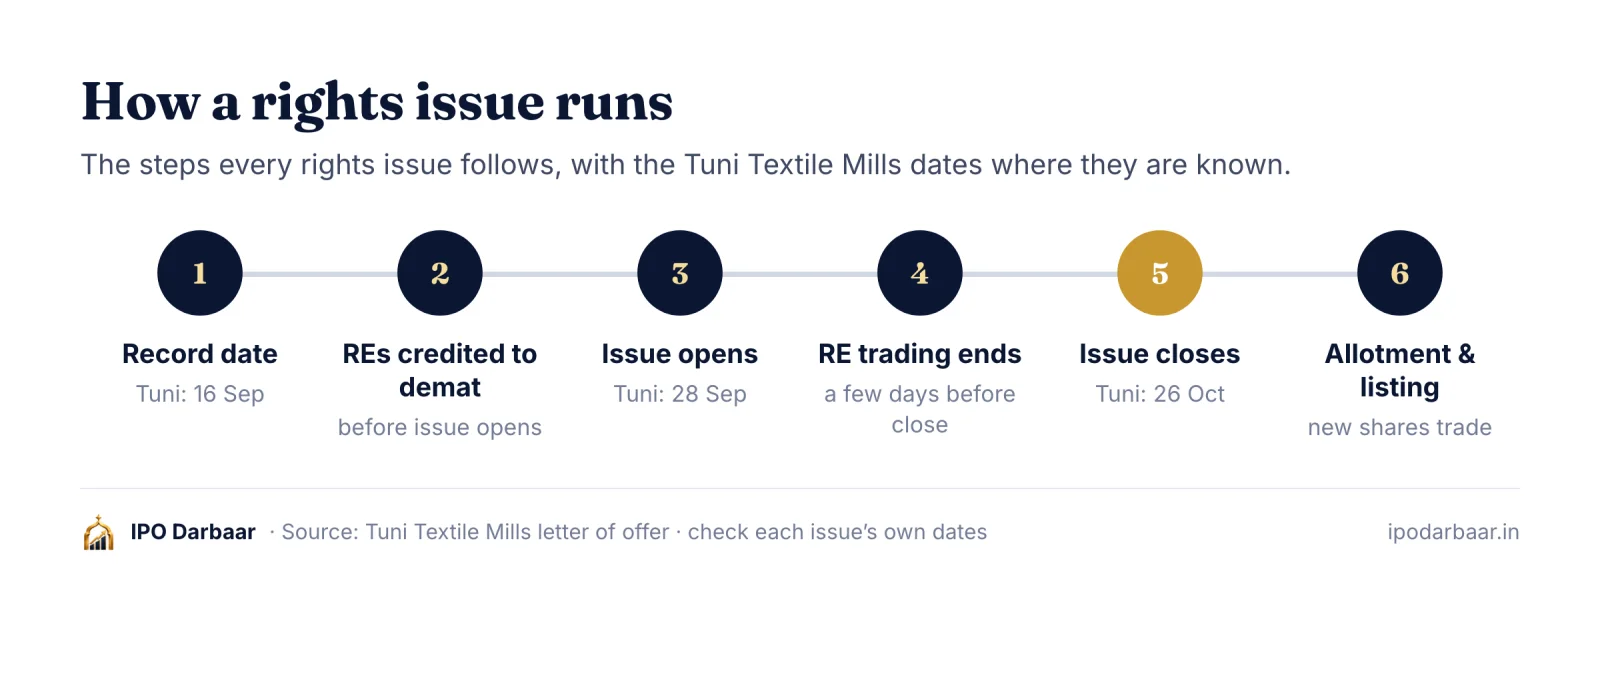
In a rights issue, the company decides how much it wants to raise, the price of the new shares and the ratio in which they are offered. Only shareholders who held shares at the end of the record date are eligible. Each eligible shareholder receives rights entitlements, which can be used to buy the new shares, sold to someone else, or left to lapse.
Unlike an IPO, there is no allotment lottery for your entitlement: if you apply for the shares you are entitled to and pay on time, you get them.
Why companies choose a rights issue
A rights issue lets a company raise equity from the people who already own it. Compared with selling new shares to outsiders, it keeps ownership with existing shareholders, usually costs less to run than a public offer, and can be completed without bringing in new investors. Companies use rights issues to cut debt, fund expansion or strengthen their balance sheet after losses. When promoters subscribe to their full entitlement, or say they will take up unsubscribed shares, it is often read as a sign of their confidence; when they stay away, it is worth asking why.
Key terms
- Ratio: how many new shares you can buy for the shares you hold. A 3:19 ratio means 3 new shares for every 19 held.
- Record date: the date on which you must hold shares to be eligible. Shares bought after that date do not carry the right.
- Issue price: the price of each new share, usually at a discount to the market price.
- Rights entitlements (REs): the right to apply, credited to your demat account as a separate security before the issue opens.
- Renunciation: selling or transferring your REs to someone else, either on the stock exchange or off-market.
- Partly paid shares: shares where you pay part of the price on application and the rest in one or more later "calls".
- Letter of offer: the document with the full terms, dates and application process.
Fractional entitlements
Ratios rarely divide your holding exactly. With a 3 for 19 ratio, 100 shares entitle you to 100 × 3 ÷ 19 = 15.79 rights shares. Entitlements are usually rounded down to whole shares, so you would get 15. The letter of offer explains how fractions are handled in that issue.
Rights issue vs bonus issue vs FPO
| Rights issue | Bonus issue | Follow-on public offer (FPO) | |
|---|---|---|---|
| Who gets it | Shareholders on the record date | Shareholders on the record date | Anyone who applies |
| Do you pay? | Yes, the issue price | No, the shares are free | Yes, the offer price |
| Does the company get money? | Yes | No, reserves are turned into share capital | Yes |
| Your stake if you do nothing | Falls | Unchanged | Falls |
Example 1: Tuni Textile Mills, 15 for 4 at ₹1
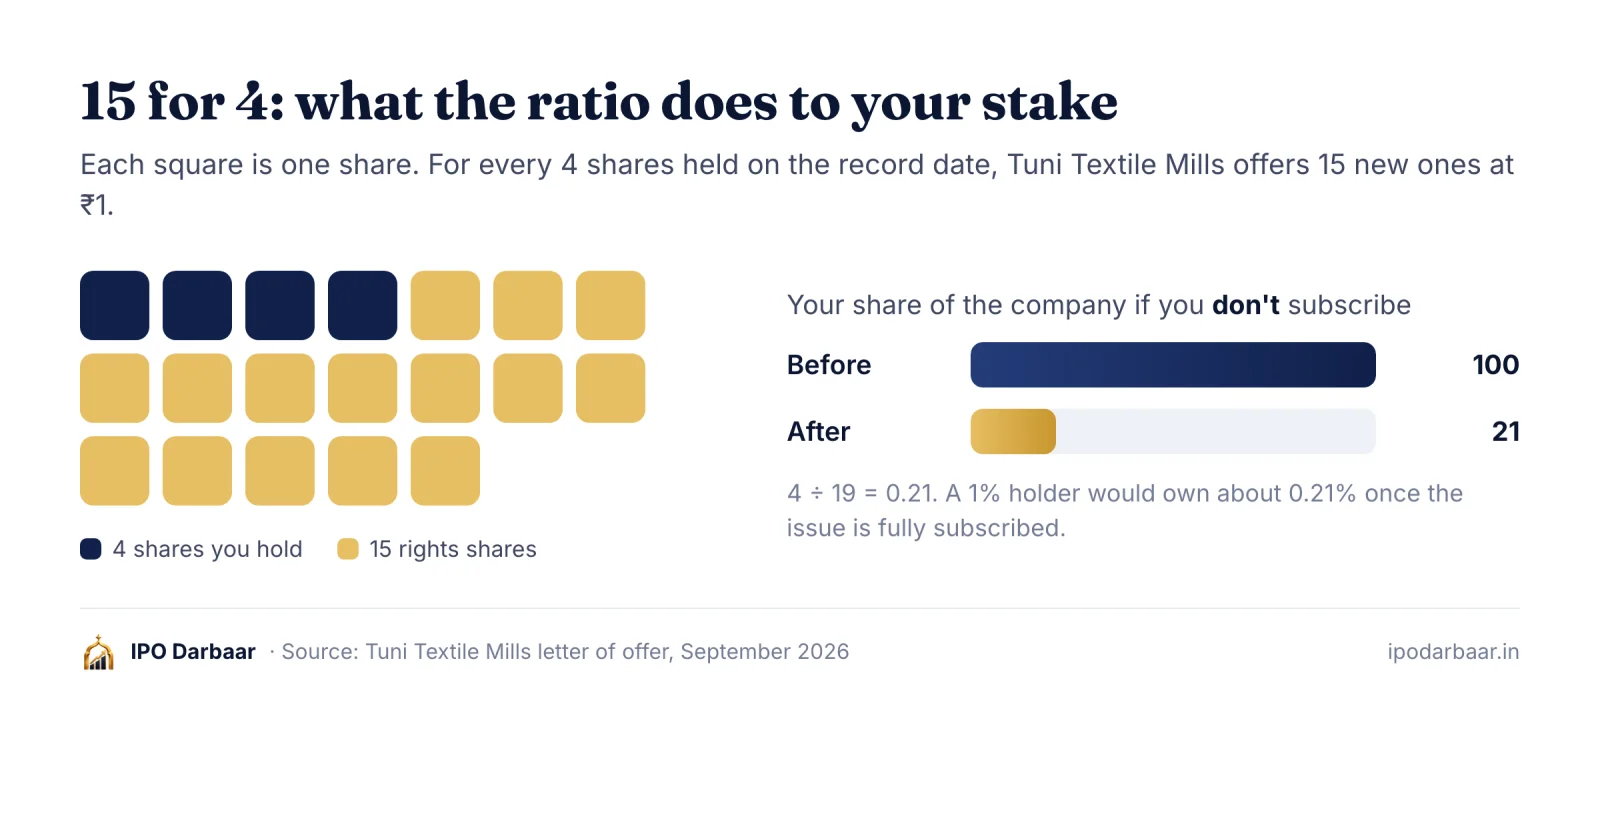
Tuni Textile Mills is offering up to 48,98,66,250 shares of face value ₹1 at ₹1 each (at par), for up to ₹48.99 crore. Shareholders on the record date, 16 September 2026, get 15 rights shares for every 4 held. The issue is open from 28 September to 26 October 2026.
| Shares held on record date | Rights shares | Amount to pay |
|---|---|---|
| 400 | 1,500 | ₹1,500 |
| 1,000 | 3,750 | ₹3,750 |
| 4,000 | 15,000 | ₹15,000 |
A ratio this large changes the ownership of the company. If the issue is fully subscribed, every 4 existing shares become 19. A shareholder who does not subscribe keeps the same number of shares, but their percentage holding falls to 4/19, or about 21% of what it was.
Example 2: Jaykay Enterprises, 3 for 19 at ₹75, partly paid
Jaykay Enterprises offered up to 2,05,71,642 partly paid-up shares of face value ₹1 at ₹75 each (including a premium of ₹74), for up to ₹154.29 crore. Shareholders on the record date, 28 August 2026, got 3 rights shares for every 19 held, and the issue ran from 7 to 18 September 2026.
Half the price was payable on application and the rest in one or more later calls. For a shareholder with 1,900 shares:
| Step | Calculation | Amount |
|---|---|---|
| Rights shares | 1,900 × 3 ÷ 19 | 300 shares |
| Total price | 300 × ₹75 | ₹22,500 |
| Paid on application | 300 × ₹37.50 | ₹11,250 |
| Paid later in calls | 300 × ₹37.50 | ₹11,250 |
Partly paid shares trade separately from fully paid shares until the final call is paid. If you do not pay a call on time, the company can forfeit the partly paid shares, along with what you have already paid.
The discount is not free money
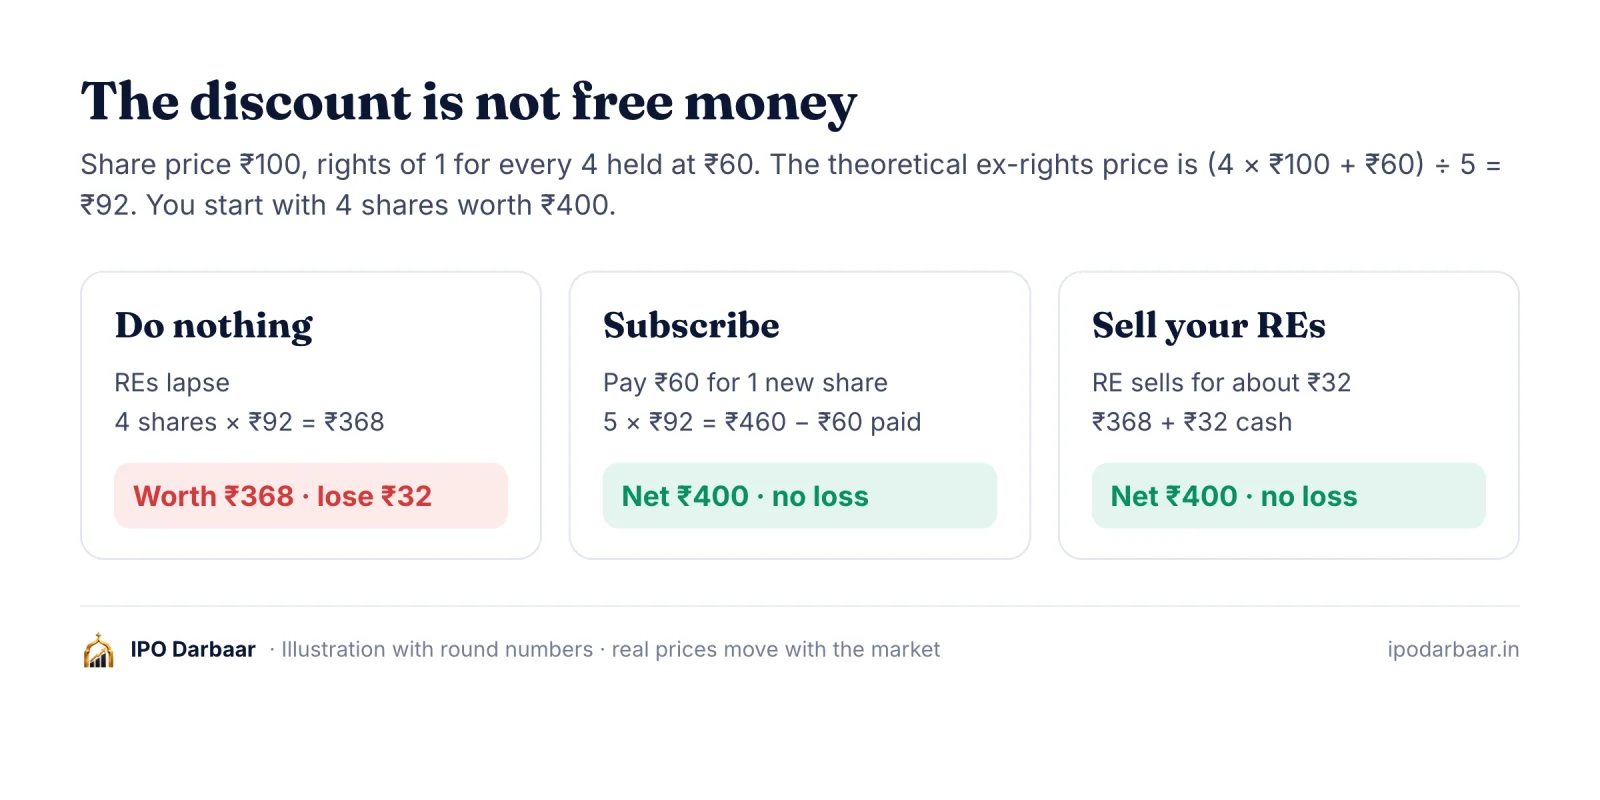
Because new shares are issued below the market price, the share price usually adjusts once the shares trade "ex-rights". The theoretical ex-rights price (TERP) shows where it should settle:
TERP = (existing shares × market price + new shares × issue price) ÷ total shares after the issue
For example, if a share trades at ₹100 and the company offers 1 new share for every 4 held at ₹60, the TERP is (4 × ₹100 + 1 × ₹60) ÷ 5 = ₹92. A shareholder with 4 shares had ₹400 of stock before; after the issue those 4 shares are worth about ₹368. They recover the ₹32 difference only by subscribing (paying ₹60 for a share worth about ₹92) or by selling their rights entitlement, which should be worth about ₹32. If they do nothing, the ₹32 is simply lost.
Your options: subscribe, sell or let lapse
- Subscribe: apply for all or part of your entitlement. Many issues also let you apply for additional shares, which are allotted from the entitlements others do not use.
- Sell your REs: if you do not want to invest more, sell your rights entitlements on the stock exchange during the RE trading window, or transfer them off-market. RE trading closes a few days before the issue closes, so check the letter of offer for the last date.
- Let them lapse: REs that are not used or sold by the time the issue closes are extinguished, and you get nothing for them. This is usually the worst option.
How to apply
Most shareholders apply through their bank's net banking using ASBA, which blocks the money until allotment, or through their broker if it supports rights issues. You need the rights entitlements in your demat account; the letter of offer and the application form sent by the registrar explain the steps and the timelines. Shareholders who hold shares in physical form should follow the specific instructions in the letter of offer.
Before applying, compare the issue price with the market price, read what the money will be used for, and decide whether you want to invest more in the company. Current rights issues are listed on our rights issue page, and our October roundup covers the NCDs and buybacks open this month. New to market terms? The IPO glossary explains the jargon.
Frequently asked questions
Who is eligible for a rights issue?
Anyone who holds the shares at the end of the record date. Because trades settle the next working day, you must buy by the trading day before the record date.
What if I sell my shares after the record date?
You keep your rights entitlements. They are worked out from your holding on the record date and credited to your demat account separately from the shares.
Can I apply for more shares than my entitlement?
In most rights issues, yes. Additional shares are allotted from the entitlements that other shareholders do not use, so you may get some, all or none of the extra shares you ask for.
What happens to rights entitlements I do not use?
If you neither apply nor sell them before the deadlines, they lapse when the issue closes and you get nothing for them.
For information and education only; not investment advice. Figures come from offer documents, exchange and SEBI filings and IPO Darbaar data as of the date of publishing. Grey market premium (GMP) is unofficial.