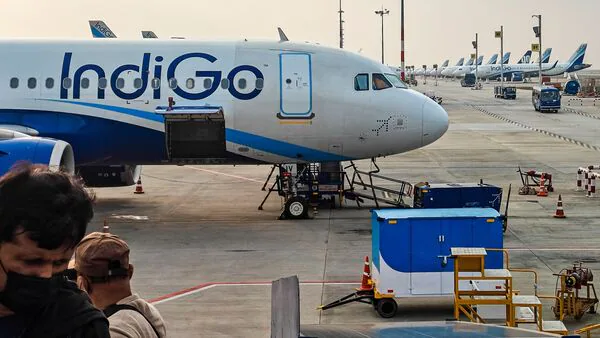
Global brokerage Jefferies has sharply reduced its price target for InterGlobe Aviation Ltd. (IndiGo) by 16.4%, even as it reaffirmed its Buy rating on the airline stock. The revision comes amid operational disruptions resulting from regulatory changes and crew shortages that have affected IndiGo’s recent performance.
Jefferies now expects IndiGo’s share price to reach ₹6,035 over the next 12 months, down from an earlier estimate of ₹7,025. Despite the downgrade, the brokerage believes the stock still offers meaningful upside from current levels.
Earnings Estimates Cut Deeply
The brokerage firm has also made substantial reductions to IndiGo’s earnings forecasts. Earnings per share (EPS) estimates for FY26 to FY28 have been slashed by 13% to 53%, reflecting a more cautious outlook. The cuts are attributed to weaker unit revenues, a reduction in near-term capacity expansion, and the lingering impact of peak-season disruptions on the airline’s financial performance.
IndiGo recently trimmed its capacity guidance for Q3 FY26, forecasting high-single-digit to early-double-digit growth in available seat kilometres, significantly lower than the previously anticipated high-teens growth. The airline also expects unit revenue to decline in the mid-single digits year-on-year, compared with earlier guidance of stable or slightly higher revenue.
Jefferies added that recovery in FY27 will depend heavily on timely aircraft deliveries and adequate pilot availability, highlighting that recent events have intensified concerns around crew sufficiency.
Buy Call Still Intact Despite Near-Term Pressure
While Jefferies revised both the price target and earnings forecasts, it maintained its Buy call for several reasons:
IndiGo’s long-standing record of strong operational execution
Ongoing opportunities for international network expansion
The recent fall in share price, which the brokerage believes already factors in the operational disruptions
The firm also noted that the long-term impact on customer sentiment will depend on how swiftly IndiGo restores operational stability. Historically, passenger confidence in airlines tends to rebound once schedules normalise.
Stock Performance
IndiGo shares have shown notable volatility. Over the past five sessions, the stock has dropped around 6.5%. However, it remains up 16.5% over the past month and 11.7% over the past six months, also recording an 8.4% gain over the past year, marking steady returns for longer-term investors.
This news is for information only and is not investment advice. Please do your own research before making investment decisions.